
Options Greek Cheat Sheet
The options Greeks are five measurements that show how an option's price reacts to the forces that move it: Delta (stock price), Gamma (how fast Delta changes), Theta (time passing), Vega (implied volatility), and Rho (interest rates). Traders use them to pick strikes, gauge risk, and decide when to close or roll a trade.
This cheat sheet covers all five. Each section gives you the definition, the characteristics that matter in a real position, a worked example, and a chart, so you can see how these metrics move option prices and shape your strategy. I have spent 22 years trading derivatives, so where it helps, I have also added how I actually use each Greek to pick strikes, roll trades, and decide what to do around earnings.
Key Takeaways
✅ Delta measures how much an option moves per $1 change in the stock, and doubles as a rough probability that the option finishes in the money. It is not the probability of profit.
✅ Gamma shows how fast Delta itself changes. It peaks for at-the-money options close to expiration, which is exactly where short options get risky.
✅ Theta is daily time decay. It is negative when you own an option and positive when you sell one, and it accelerates as expiration nears.
✅ Vega measures sensitivity to implied volatility, which can move option prices even when the stock does not move. It is why options lose value right after earnings.
✅ Rho (interest-rate sensitivity) matters least for short-term traders but rounds out the five standard Greeks.
✅ My starting rules: sell about 30 delta on covered calls (about 25 on puts), about 30 days out, roll a short call when it reaches 70 delta, and do not sell options in front of earnings.
Want a printable Greeks reference? The free 2-page PDF summarizes the five Greeks, their signs by position, and the theta decay curve, plus a greeks-by-DTE card and a pre-trade checklist.
⬇️ Download the Free Cheat Sheet (PDF)
Instant download. No email required.
Option Greeks Chart: All Five at a Glance
Here is the whole list on one chart. The sign columns show whether each Greek is positive (+) or negative (−) for the position, depending on whether you bought or sold the option.
Selling an option flips every sign, which is why sellers collect theta and buyers pay it. There are rare exceptions (a deep in-the-money put can show a small positive theta), but the signs above hold for everyday trading.
Delta (Δ)
Δ Definition
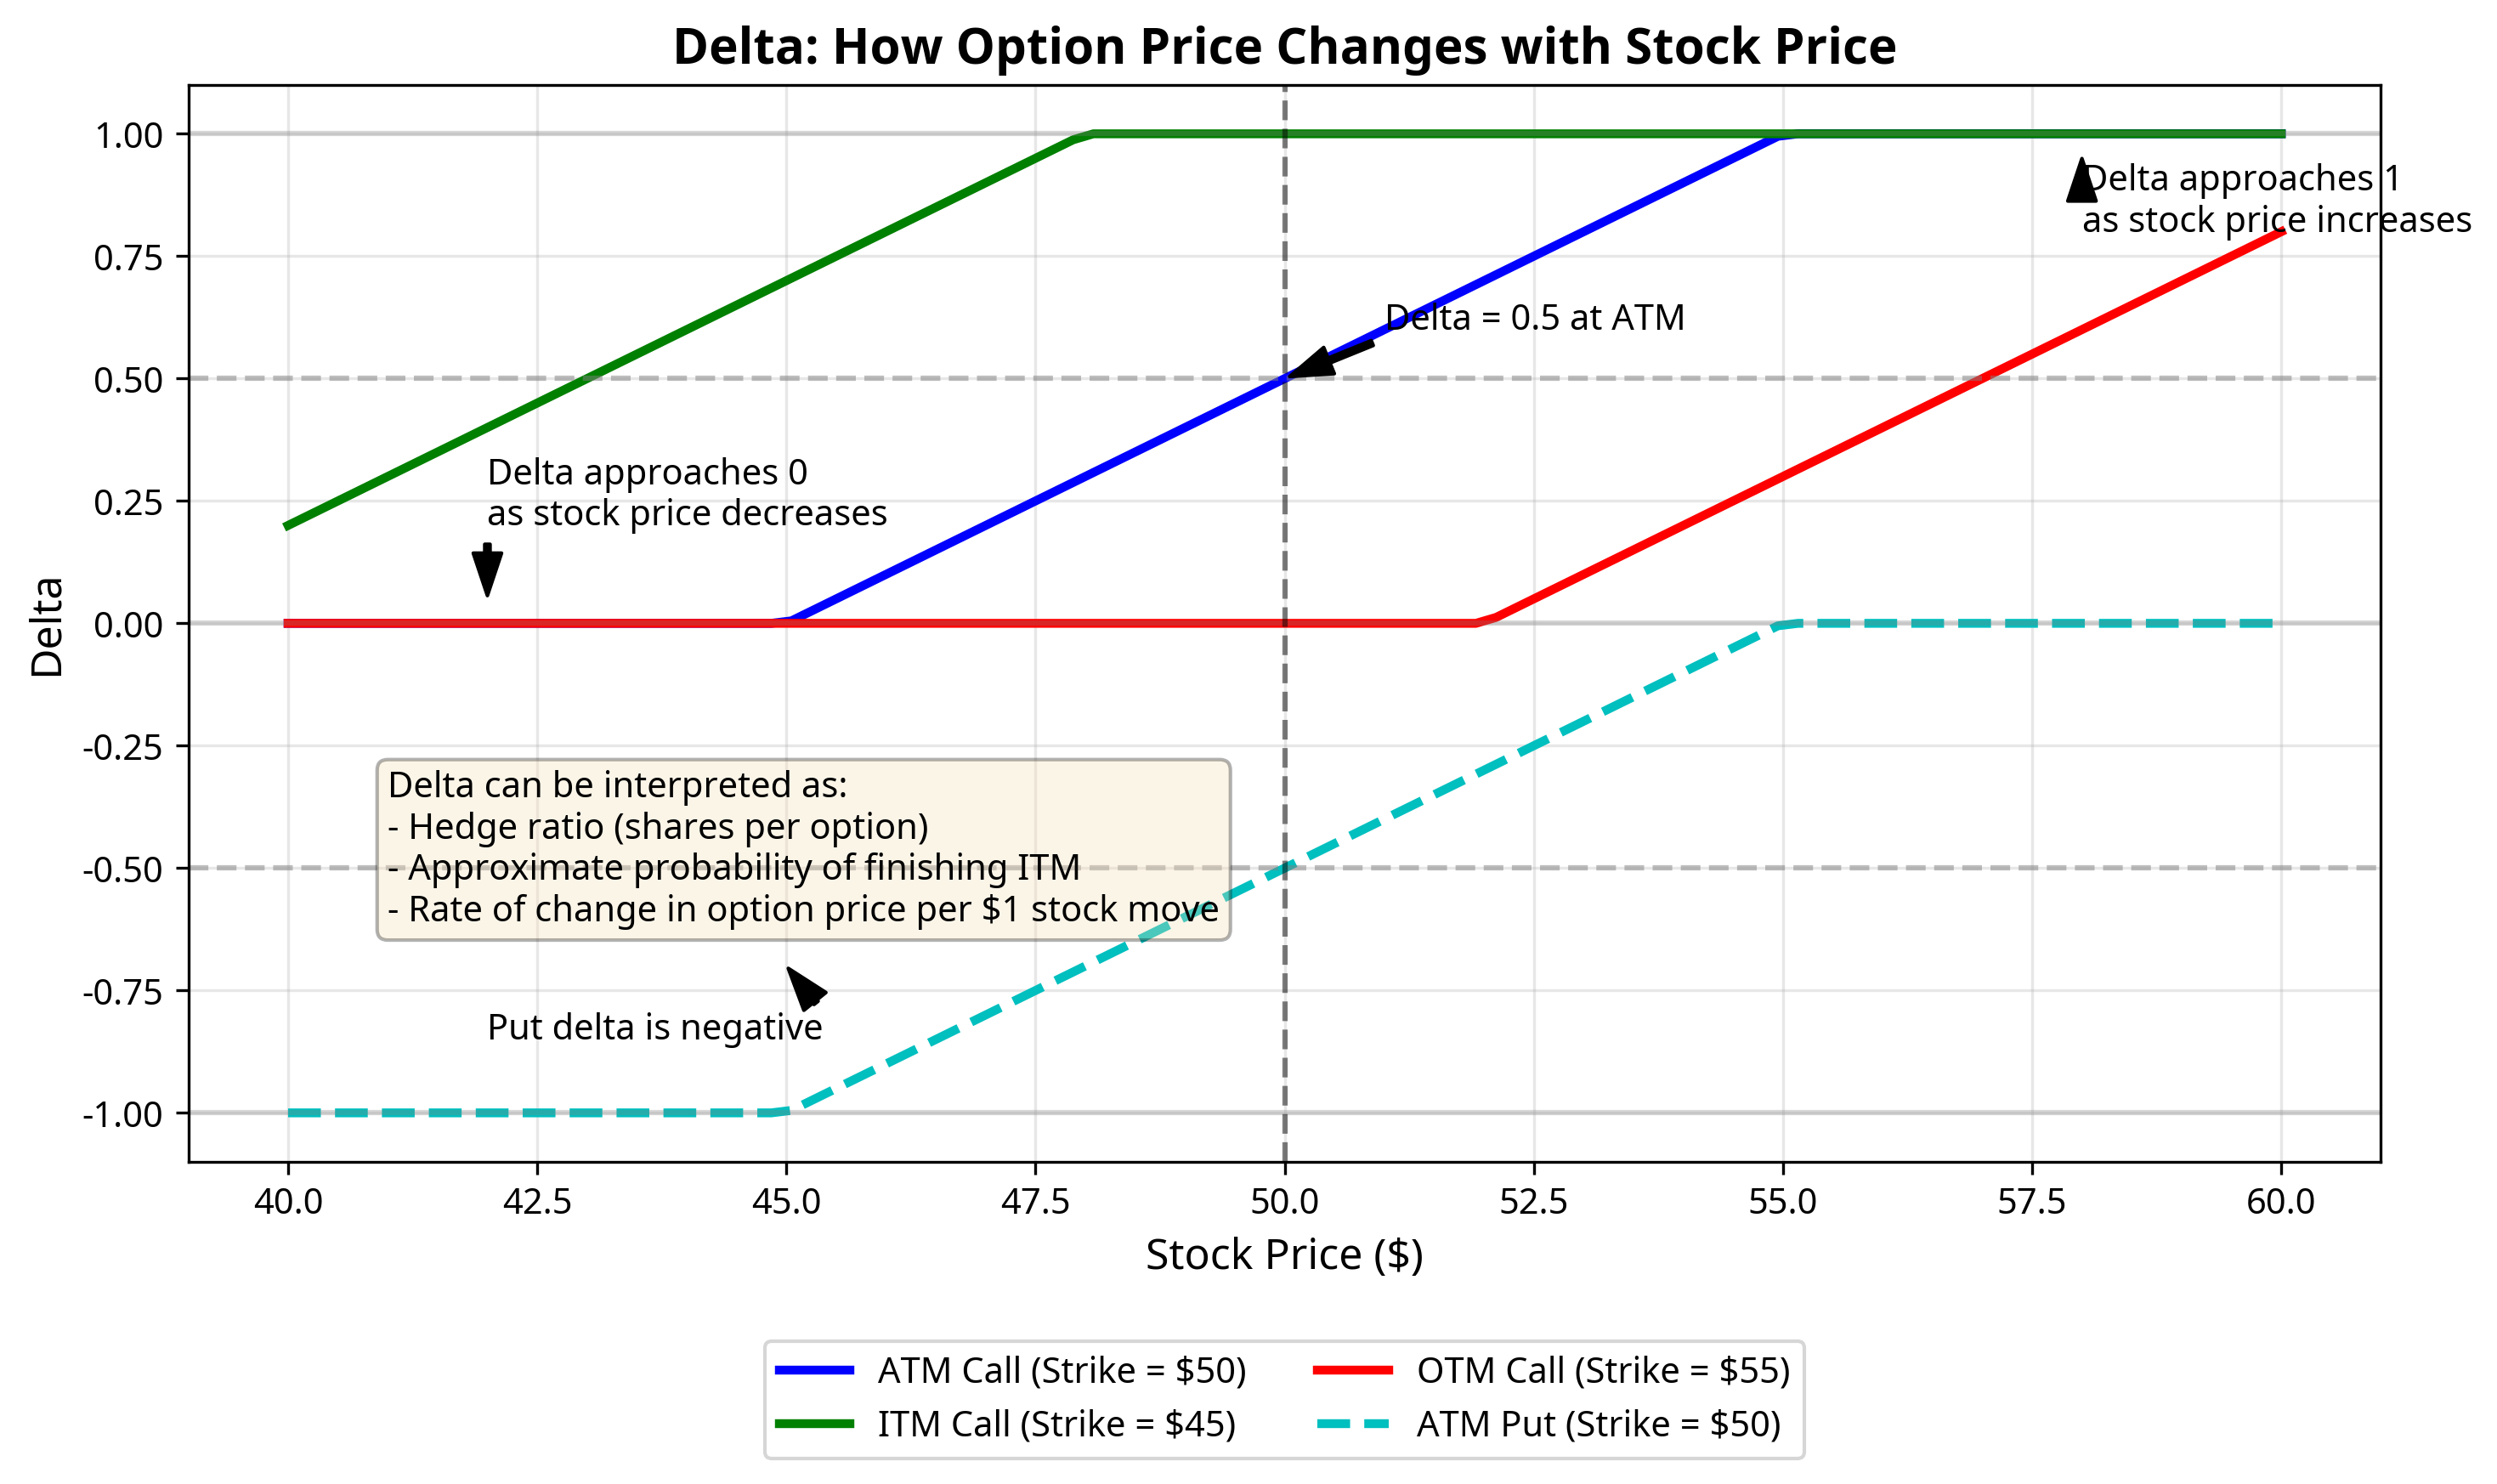
Delta measures the change in an option's price from a $1 change in the underlying security. It is often called the most important of the Greeks. When I explain it to students, I give them two ways to read it: price sensitivity and rough probability.
Characteristics
- For call options, delta ranges from 0 to +1.00
- For put options, delta ranges from 0 to -1.00
- A delta of 0.50 means the option price will move about 50 cents for every $1 change in the stock price
Practical Example
If you own a call option with a delta of 0.40 and the stock price increases by $1, your option should gain about 40 cents in value (provided the other Greeks remain the same).
The opposite happens if the stock falls, you'd lose about 40 cents.
Delta as an Indicator of Probability
Traders also use delta as a rough estimate of the chance that an option finishes in the money at expiration:
- A call option with a 0.30 delta suggests about a 30% chance of finishing in the money.
- A call option with a 0.70 delta suggests about a 70% chance of finishing in the money.
- At-the-money options typically have deltas around 0.50, suggesting roughly a 50/50 chance.
In the money is not the same as profitable. A call buyer needs the stock above the strike plus the premium paid, the break-even price, so the buyer's odds of profit are lower than delta suggests. For a seller, 100 minus delta is the rough chance the option expires worthless and you keep the full premium. The Options Industry Council's delta guide also shows how time and implied volatility shift delta, which is why it is an estimate and not a promise.
Delta is also how you measure the directional risk of an option or a whole strategy. For buyers, low-delta options are the speculative ones: they are cheap because they need a big move. One of the most common ways I see beginners misjudge risk is confusing a cheap option with a low-risk one, like buying a 10 delta call because it costs little. For sellers, a lower delta means better odds and less premium.
How I Use Delta to Pick Strikes: The 30 Delta Rule
When I sell an option, I let delta pick the strike. For covered calls, I sell about 30 delta, about 30 days out. A 30 delta call has roughly a 30% chance of finishing in the money, which means roughly a 70% chance it does not. That is not the same as low risk. You still own the shares, and if the stock falls, the loss on them can be far larger than the premium you collected.
I did not pick 30 delta at random. It came from backtesting. We tested selling covered calls at 10, 15, 40, 45 and 50 delta. Thirty delta was the sweet spot: in our testing it gave the best return while still giving the stock room to move up. A backtest describes the past. It does not guarantee future results. Sell closer to the money and your shares get called away too often. Sell too far out and the premium is so small that returns lag over time.
Delta also adjusts for volatility on its own. When implied volatility is high, the 30 delta strike sits further from the stock price; when volatility is low, it sits closer. Picking by delta builds that buffer in without any extra math. For puts I sell, I usually look around 25 delta, sometimes up to 30 and as low as 20. When I buy calls, I stay near the money, around 40 to 50 delta, rather than reaching for cheap out-of-the-money strikes.
Delta in Action: A $100 Call Example
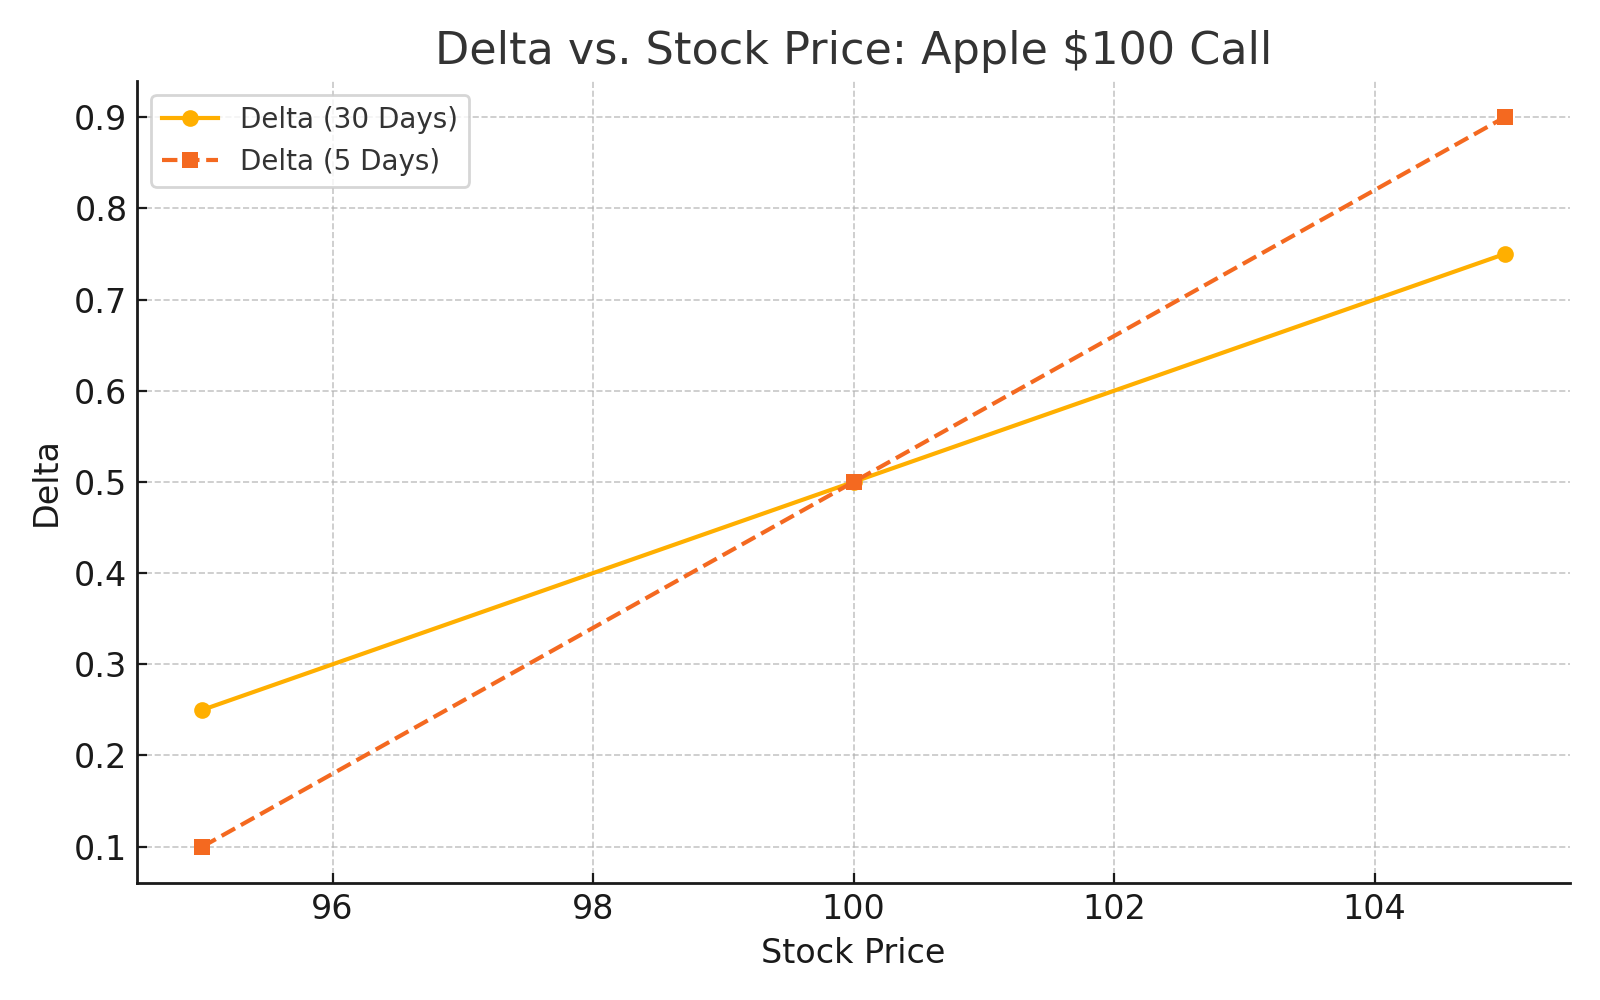
Here is a $100-strike call at three stock prices and two expirations. The values are illustrative, from a standard pricing model at 30% implied volatility, rounded. Notice how delta spreads apart as expiration approaches: out-of-the-money calls head toward 0 and in-the-money calls head toward 1.
Chart: Delta vs. Stock Price
How Traders Use Delta
⚡ A deep in-the-money call (Delta 0.80+) moves almost dollar-for-dollar with the stock, which suits a strong directional view.
⚡ A 0.20 Delta put you sell has roughly an 80% chance of expiring out of the money (worthless), and about a 20% chance it finishes in the money.
⚡ Delta is also a position-sizing tool: five contracts at 0.20 Delta give you about the same exposure as 100 shares at that moment. Gamma changes that as the stock moves, so recheck it.
Gamma (Γ)
Γ Definition
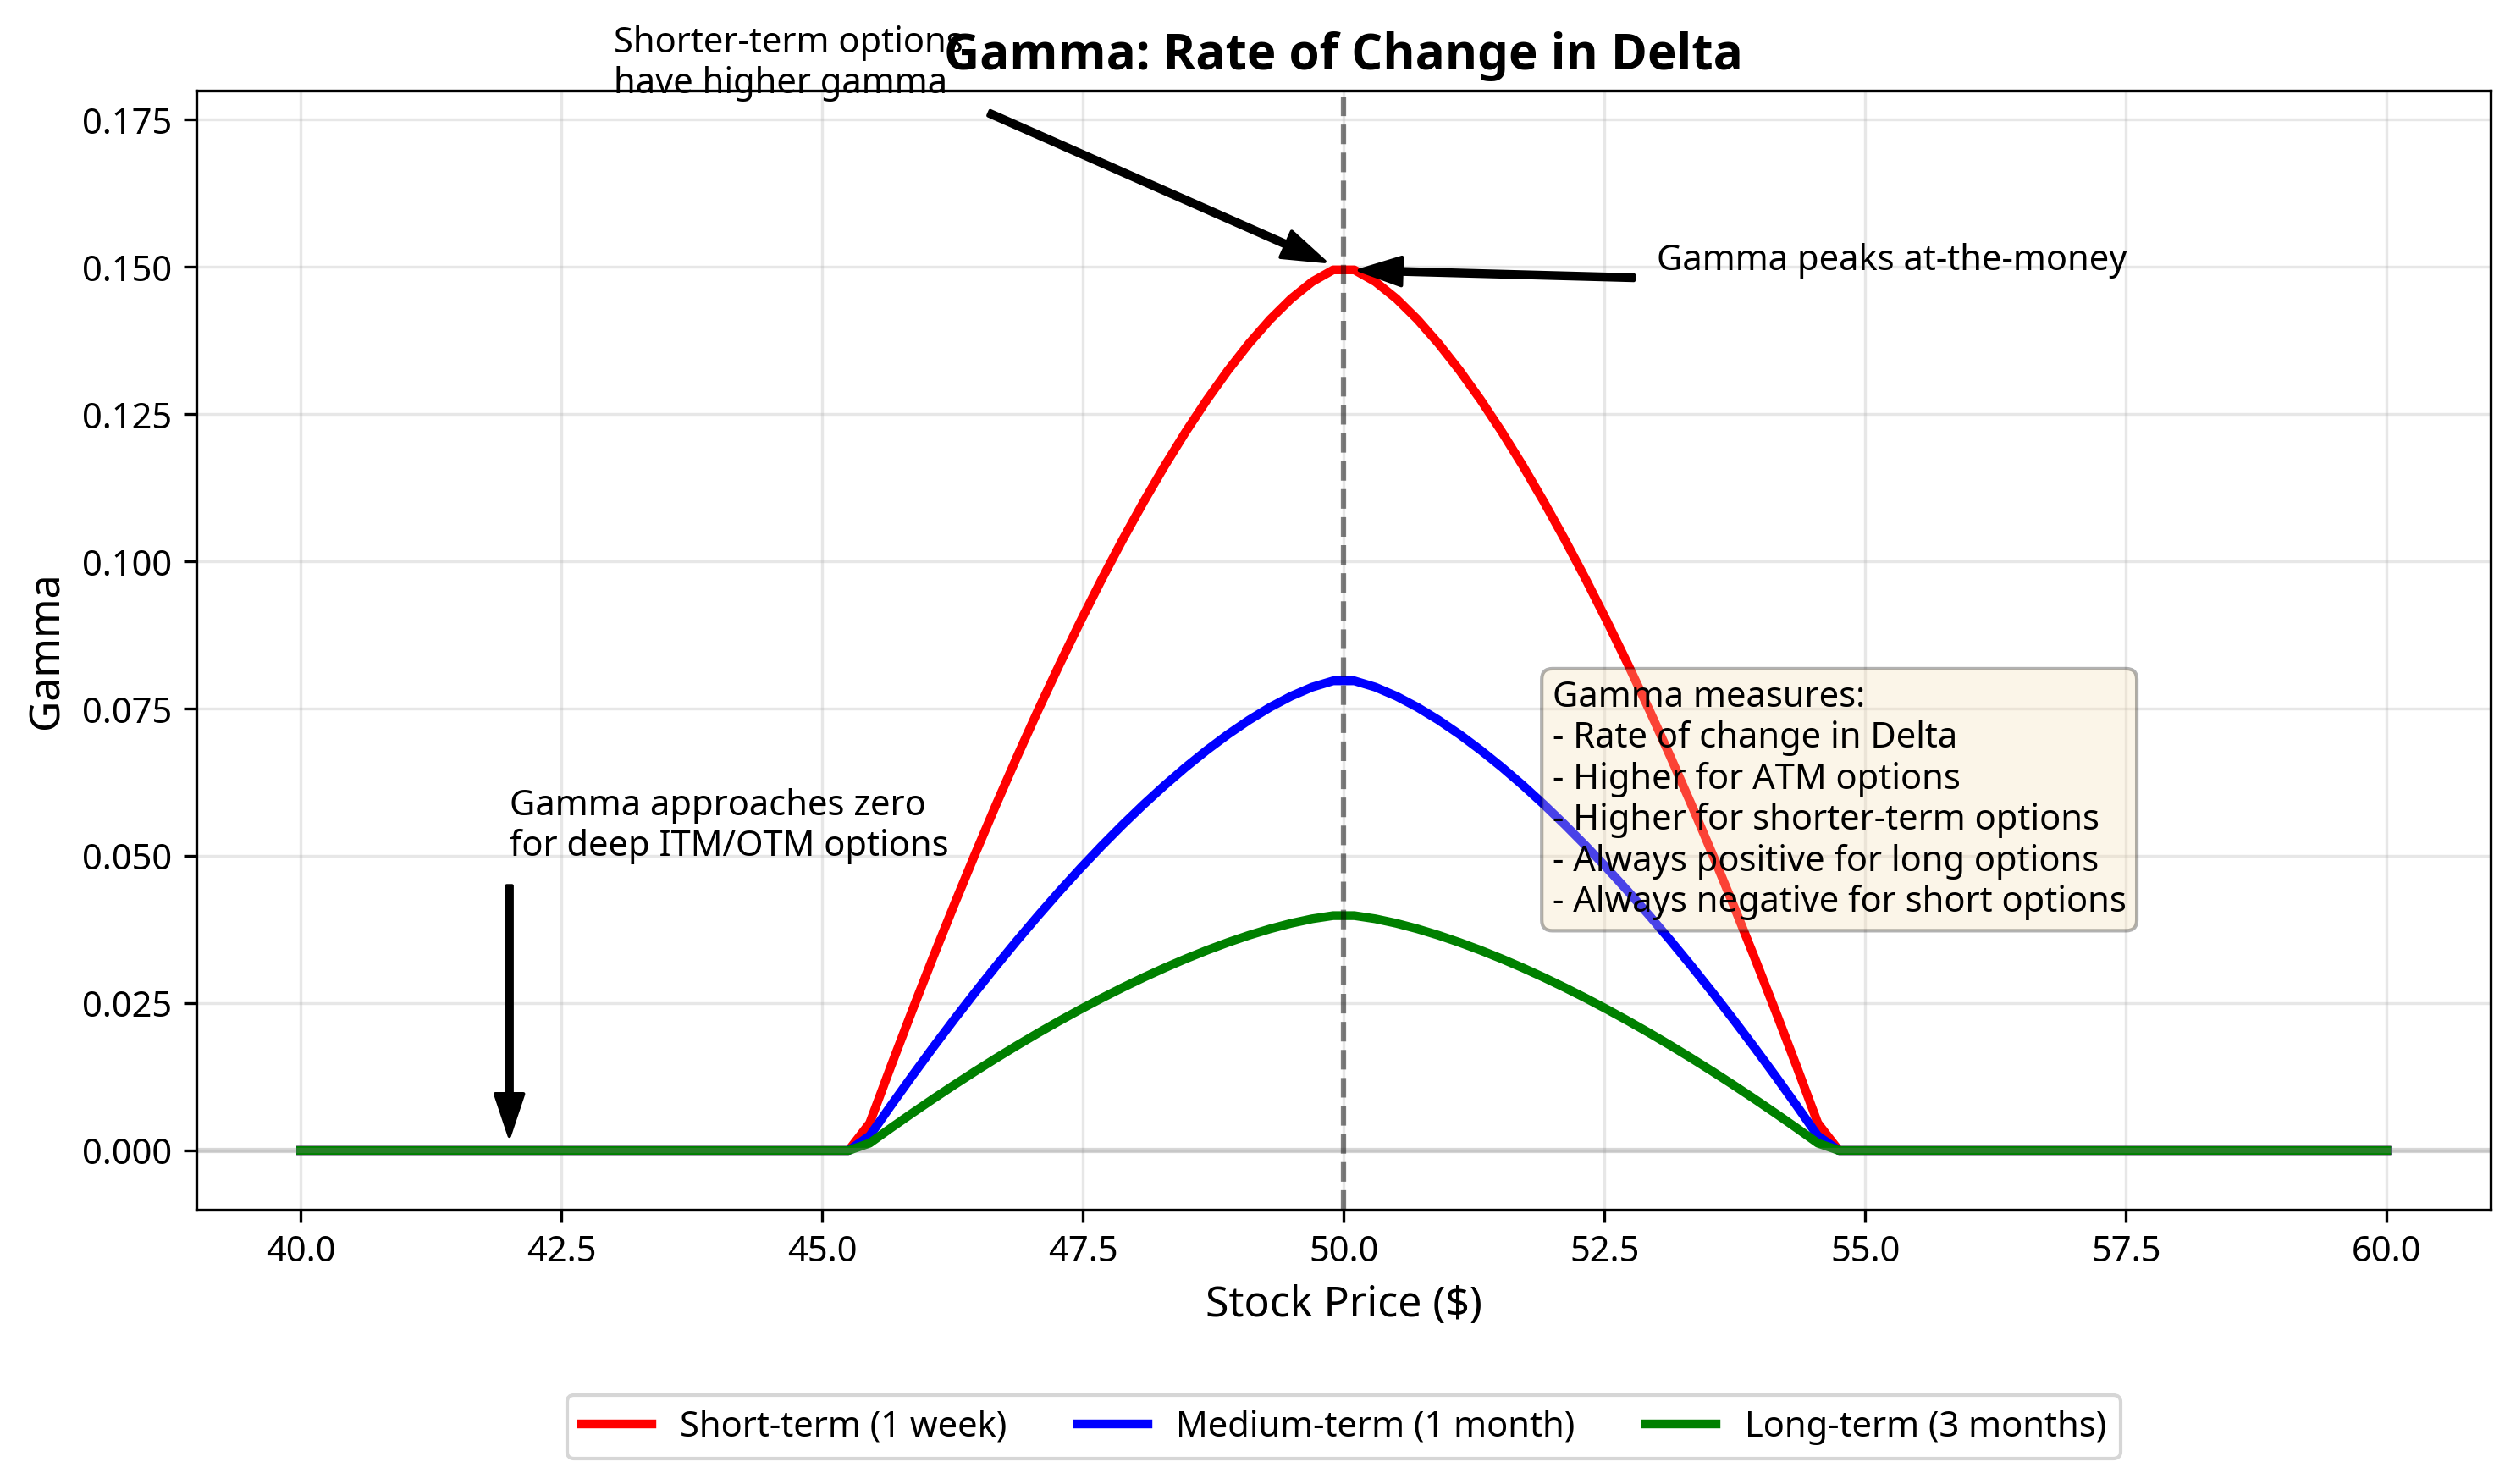
Gamma tells you how quickly delta will change when the stock price moves. Gamma values are highest for at-the-money options and lowest for those deep in-the-money (ITM) or out-of-the-money (OTM).
Characteristics
- Gamma is always positive for long options (whether calls or puts)
- Gamma is always negative for short options
- Gamma is highest for at-the-money options, and at-the-money gamma climbs as expiration gets closer
- Gamma approaches zero for deep ITM or OTM options
Practical Example
Let's say you own a call option with the following details:
- Delta: 0.50
- Gamma: 0.05
If the stock rises $1, then the following occurs:
- Delta will increase by about 0.05 to 0.55
- Your option will gain a little over 50 cents, because delta rises during the move
- Future moves will have a slightly bigger impact because of the higher delta
Risk Implications
Suppose that two options have the same delta value, but one option has a high gamma, and one has a low gamma. If you sold the options, the one with the higher gamma carries more risk, because an unfavorable move makes delta grow against you faster. If you bought them, the higher gamma works in your favor.
High gamma values mean that the option tends to experience volatile swings, which is bad for traders looking for predictable prospects.
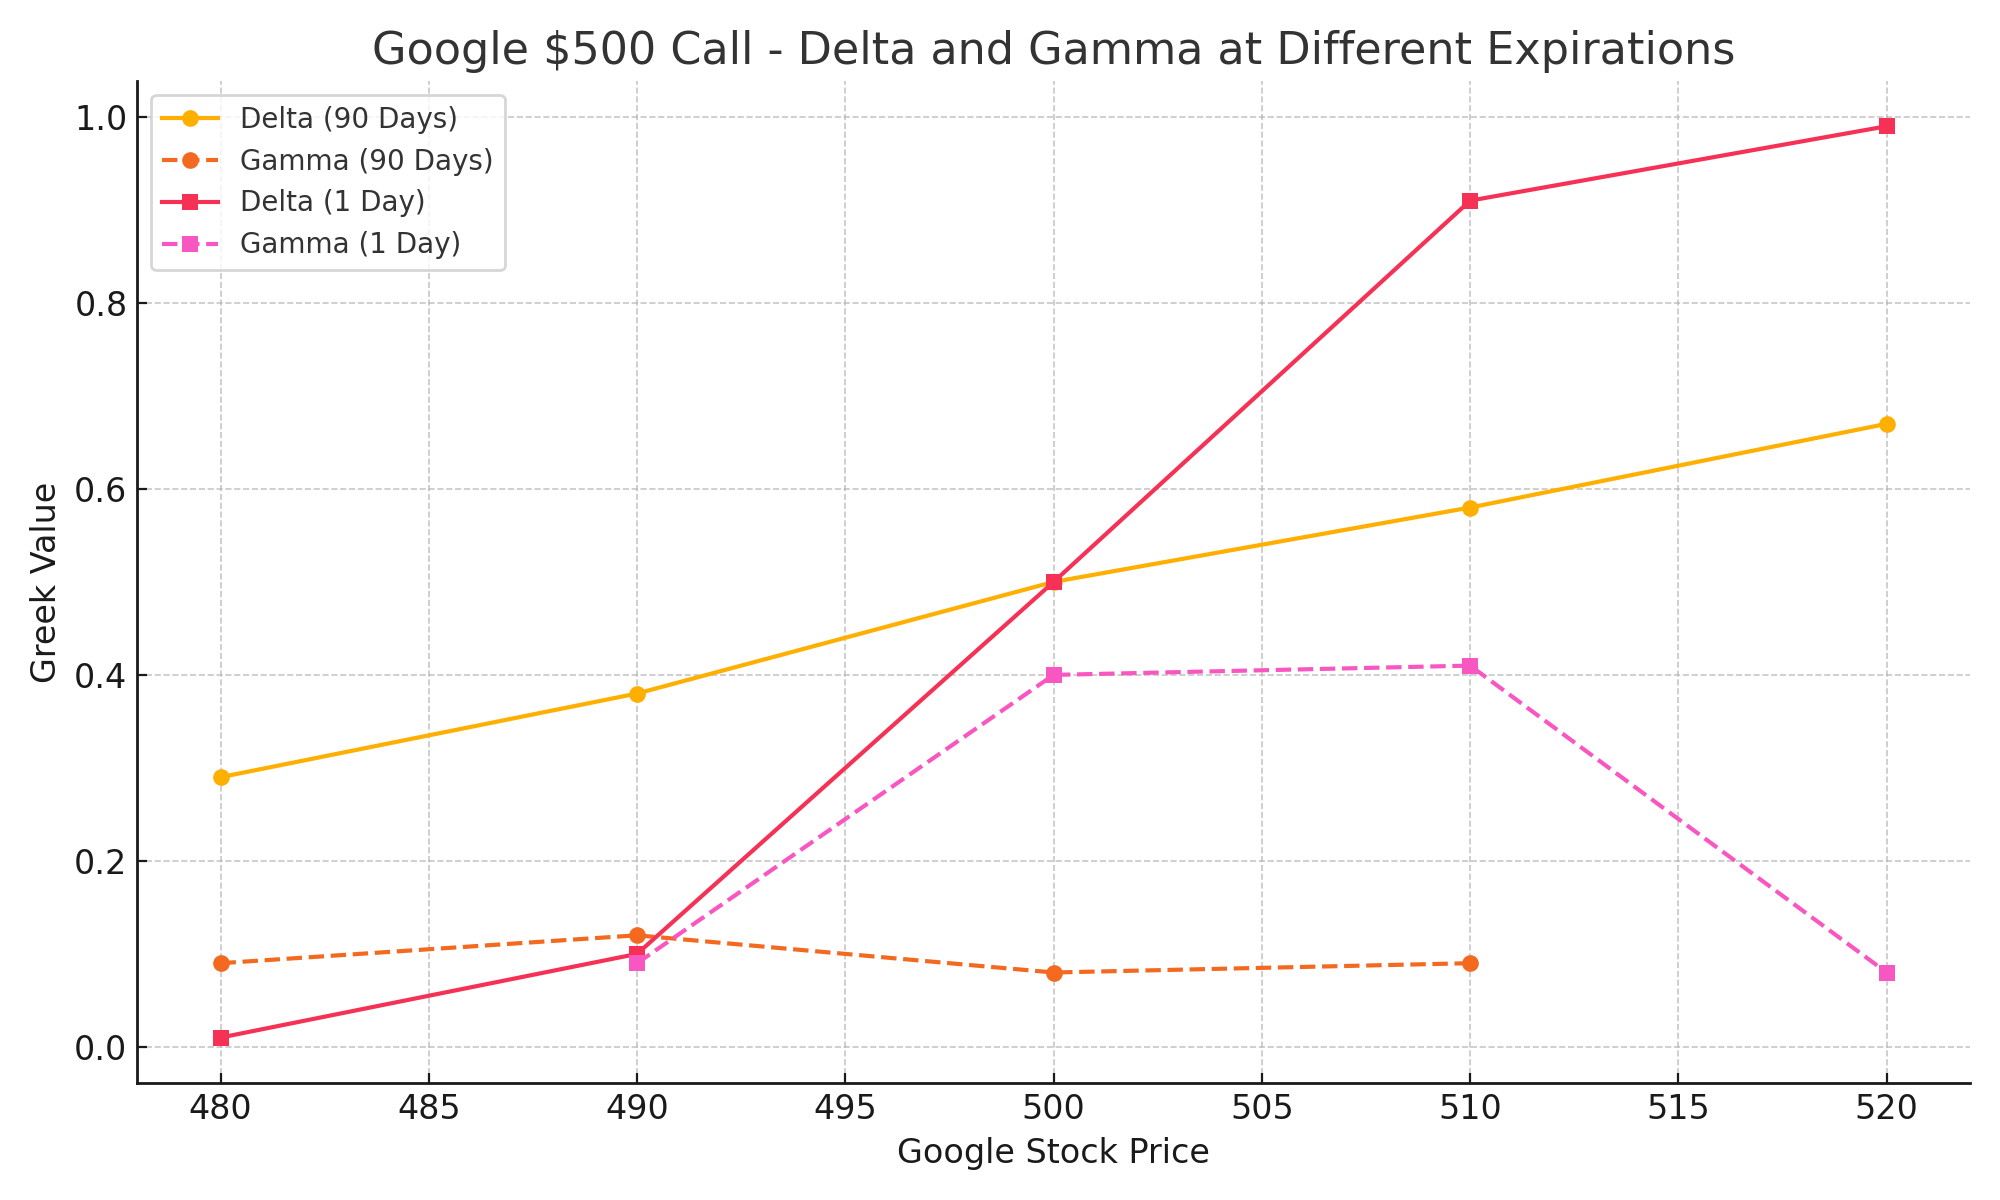
Gamma in Action: $500 Calls at 90 Days vs. 1 Day
Let's compare how Gamma behaves for a $500-strike call with 90 days until expiration versus 1 day until expiration. The values are illustrative, from a standard pricing model at 30% implied volatility, rounded. Gamma is shown as the change in delta for a $1 move in the stock.
90 Days Until Expiration
1 Day Until Expiration
At 90 days, gamma is small and nearly flat (with this much time left, it actually peaks a little below the strike), so delta drifts slowly as the stock moves. With 1 day left, at-the-money gamma is roughly ten times higher, and delta jumps from 0.10 to 0.90 across a $20 range. That is what gamma risk looks like.
Chart: Delta and Gamma at Different Expirations
How Traders Use Gamma
⚡ Shorter-dated options carry higher Gamma, especially at the money, so Delta moves faster as the stock moves.
⚡ If you are buying options, high Gamma works for you: get the direction right and the position accelerates.
⚡ If you are selling options, high Gamma is the risk. Delta grows quickly against you, which is why short positions get twitchy near expiration.
Gamma is the reason I do not like holding short options into the final days. If you sold a put and the stock is sitting near your strike with a few days left, one bad day can turn a nice gain into a loss or an assignment. For income trades, it is often better to close or roll early than to wait for expiration.
Theta (Θ)
Θ Definition
Theta measures the rate of time decay in the value of an option or its premium. It is roughly how much an option's price drops each day as time passes, all else equal.
Characteristics
- As time passes, there is less time for a big move, so an option's time value shrinks
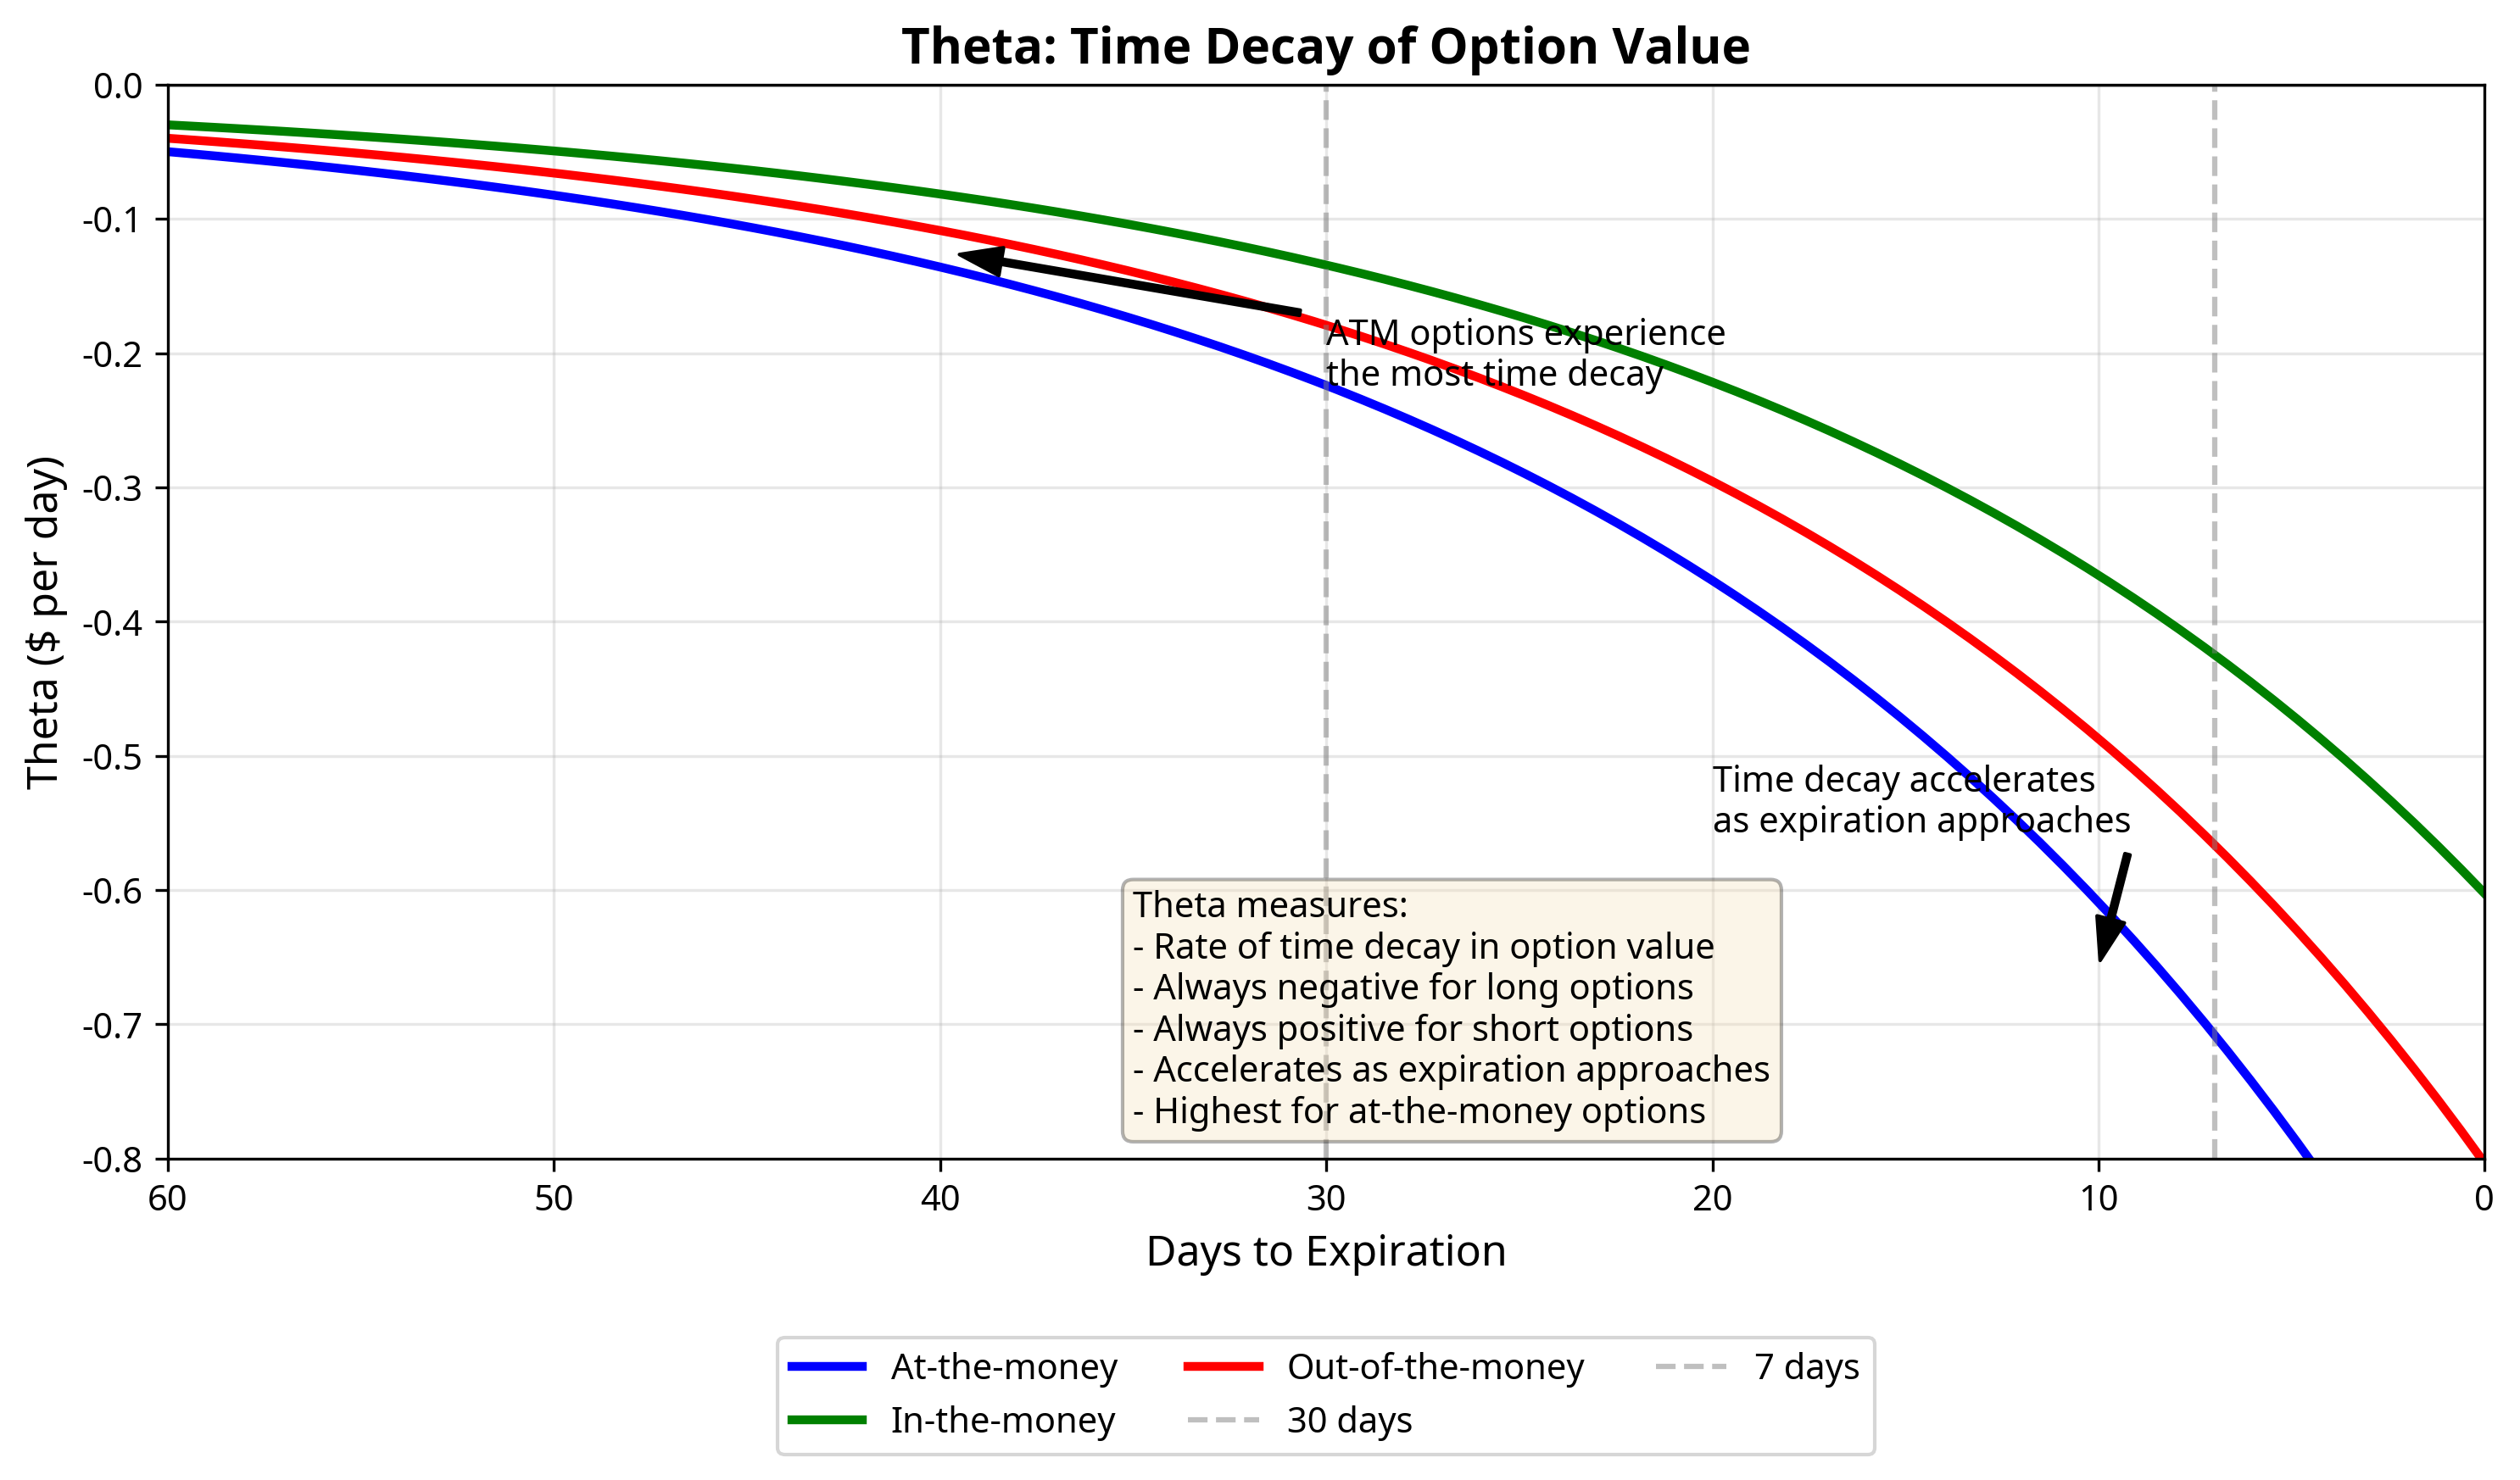
- Time decay tends to accelerate as the expiration date draws closer
- Theta is negative for options you own and positive for options you sell, because time value only drains in one direction: buyers pay it and sellers collect it
- Theta is generally good for sellers and bad for buyers
Is Theta Positive or Negative?
Both, depending on your side of the trade. Your platform shows theta for one long contract, usually as a negative number such as -0.05, meaning the option loses about $5 per contract per day. If you sold that option, your position theta is +0.05: that same $5 a day is decaying in your favor.
How Fast Does Theta Decay Near Expiration?
An option premium with no intrinsic value will decline at an increasing rate as expiration nears.
The table below shows theta at different points in the life of an at-the-money S&P 500 index call with a 930 strike, a historical example from when the index traded near that level. Theta is shown in dollars per contract per day, lost by the buyer:
As you can see, theta increases as the expiration date gets closer. At T+19 (six days before expiration), theta has reached 93.30, which means the option is now losing about $93.30 per contract per day, up from $45.40 per day at T+0 when the hypothetical trader opened the position.
Trading Implications
Option buyers face a constant battle against time decay, while option sellers benefit from the passage of time. At-the-money options typically experience the most significant time decay, and this decay accelerates in the final weeks before expiration.
This is the core of how I trade. With income trades, I get paid for time and probability: I sell the option, and I want time decay to take it to zero. With a long option, I am fighting that same decay every day. If I bought a call, the stock has gone nowhere, and the option has lost value with two weeks left, I will usually sell it rather than let theta keep eating it.
Theta in Action: 30 Days vs. 5 Days to Expiration
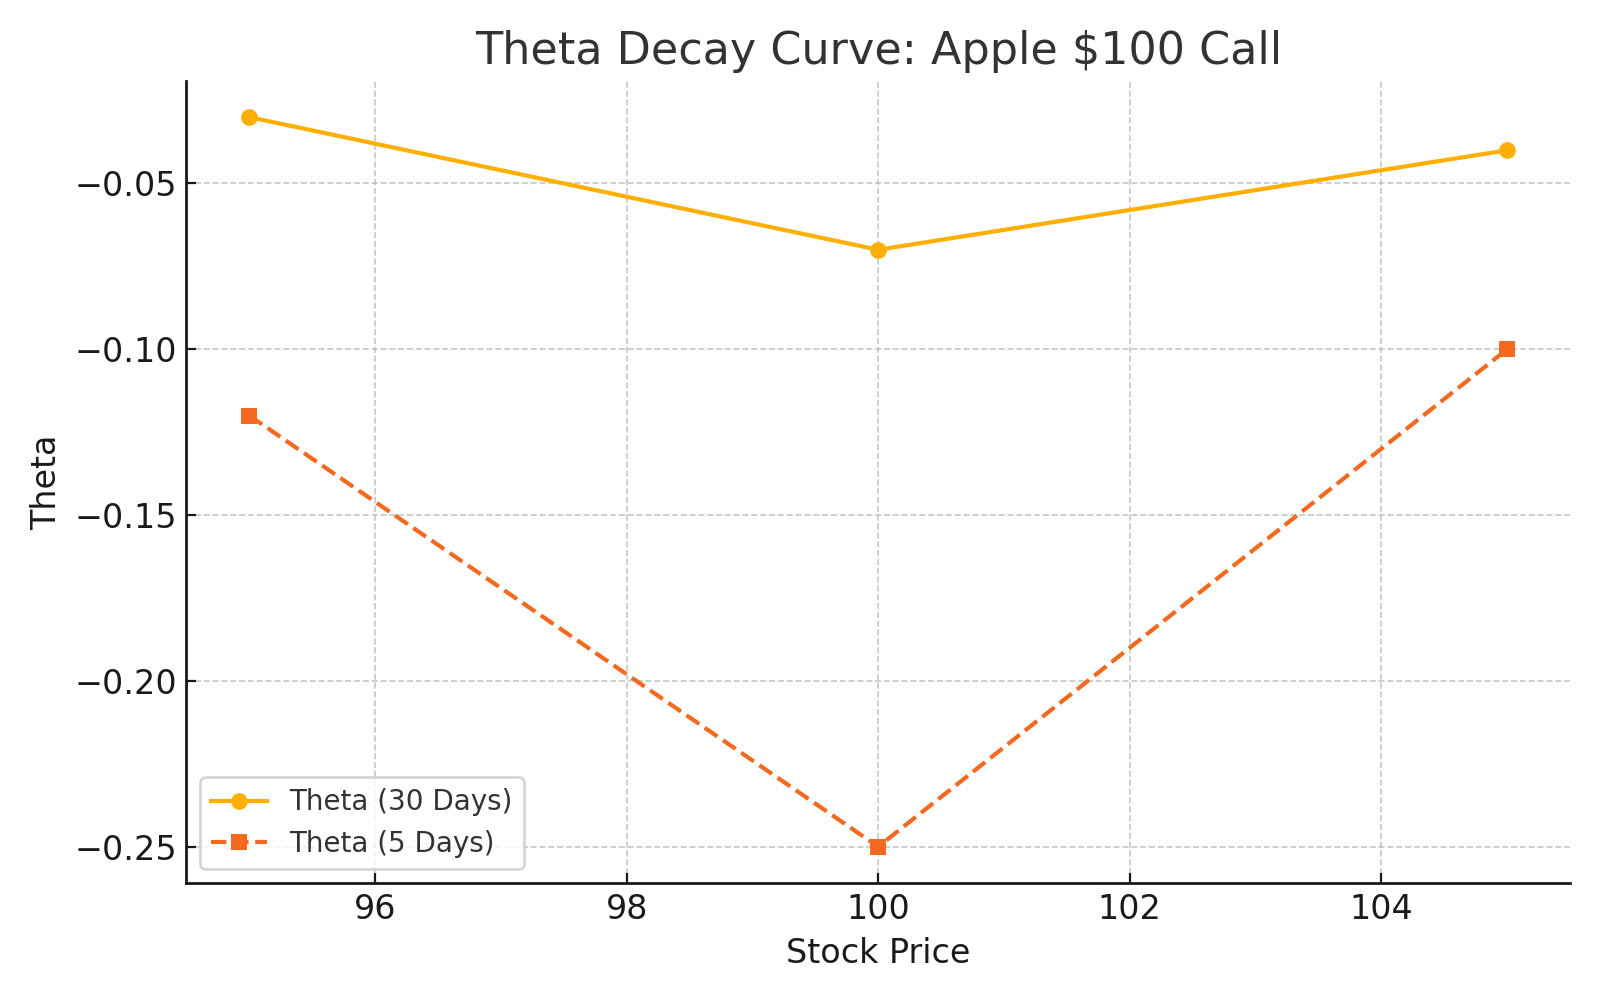
Here is the same $100-strike call compared across two expirations, 30 days versus 5 days, to show how time decay accelerates as expiration approaches. Values are illustrative, from a standard pricing model at 30% implied volatility, rounded. Theta is per share; multiply by 100 for one contract.
Watch the at-the-money row: its daily decay more than doubles in the final days. The out-of-the-money option at 5 days is worth only $0.11, and at about $0.05 a day it is close to worthless before expiration arrives. In-the-money options are mostly intrinsic value, so their theta stays modest.
Chart: The Theta Decay Curve
How Traders Use Theta
⚡ Buy a short-dated option and the stock goes nowhere, and you still lose money every day, most sharply in the final week.
⚡ Sell options (credit spreads, cash-secured puts, covered calls) and that same decay is your income.
⚡ At-the-money options decay fastest near expiration; longer-dated options bleed slowly at first, then accelerate.
Reading Delta and Theta Together on an Option Chain
Most platforms let you add Delta and Theta columns to the option chain. When I set up a trade, I pick the expiration first (about 30 days out for income trades), scroll to the Delta column to find the strike closest to my target, then review the credit I would receive. The Theta column on that same row shows how much decay you are collecting, or paying, each day. Delta tells you the odds and the directional exposure. Theta tells you what time is worth on that strike. For example, a 30 delta short put on a $100 stock might show theta around +0.05, which is about $5 a day per contract while the stock holds still.
Vega (V)
V Definition
Vega measures how much an option's price changes for a 1-point change in implied volatility. Implied volatility is the market's expectation of how much the stock will move, and it is built into every option's price.
Characteristics
- Higher implied volatility makes options more expensive, because a bigger expected move raises what the option could be worth, while the buyer's loss is still capped at the premium paid
- Option sellers benefit from a fall in implied volatility, while option buyers benefit from a rise
- Long options have a positive vega and short options have a negative vega
- An option's price can rise or fall with no change in the stock price, purely because implied volatility changed
- Vega falls as the option gets closer to expiration
Practical Example
Vega is typically expressed as the dollar amount of change in the option price for a 1-point change in implied volatility. Typical ranges for a $100 stock at about 30% implied volatility:
Trading Implications
When option prices are bid up because there are more buyers, implied volatility will increase. Long option traders benefit from pricing being bid up, and short option traders benefit from prices being bid down.
Traders can build a vega-neutral position to offset their exposure to changes in implied volatility. Options with longer expiration dates are generally more sensitive to volatility changes.

How I Learned to Respect Vega
A year or two into my career, during the dot-com run, I bought a call on an internet stock and paid a fortune for it, without understanding volatility well enough. I was right: the stock went up 20 or 30 points. But implied volatility came down, and I still lost somewhere around $10,000 to $12,000 on the trade. That is vega. Being right on direction is not enough if you overpay for volatility.
Vega in Action: 30, 15 and 5 Days to Expiration
Take at-the-money calls on a $100 stock at three different expirations (illustrative, rounded). Notice how Vega shrinks as expiration approaches:
A vega of 0.11 means a 30-day at-the-money call gains or loses about $11 per contract for each 1-point change in implied volatility.
Chart: Vega vs. Time to Expiration

How Traders Use Vega
⚡ Buy an at-the-money call right before earnings, watch the stock stay flat, and the option still loses value. That is implied volatility collapsing after the event, often called IV crush.
⚡ The mirror image is selling premium into the event to collect that crush. I do not do it, and I teach students not to: you do not know which way the stock will gap, and the move can be bigger than the market priced in.
⚡ LEAPs carry far more Vega than weeklies. Buying time means buying volatility exposure, so check where IV sits compared with where it usually trades before you enter.
⚡ My simple rule: high volatility favors selling, low volatility favors buying. When the VIX is above 20, and definitely above 25, my basic rule for beginners is to use a call spread instead of buying calls outright, so the call you sell offsets some of the expensive volatility.
Rho (ρ)
ρ Definition
Rho measures an option's sensitivity to changes in the risk-free rate of interest (the interest rate paid on US Treasury bills) and is expressed as the amount of money an option will lose or gain with a 1% change in interest rates.
Characteristics
- Rho is positive for long calls (right to buy) and increases with the price of the stock
- Rho is negative for long puts (right to sell) and approaches zero as the stock price increases
- Rho is positive for short puts (obligation to buy), and negative for short calls (obligation to sell)
- Interest rate changes impact longer-term options much more than near-term options
- The higher the price of the stock and the longer time until expiration generally means a greater sensitivity to changes in interest rates
Practical Example: Positive Rho (Call Option)
These two examples use round, illustrative numbers. A $10 premium on a $50 at-the-money option implies a long-dated, high-volatility option, which is exactly where rho matters.
⚡ Assume XYZ has a current market price of $50.00
⚡ Buying Stock Value: Buy 100 Shares XYZ at $50.00 per Share = $5,000.00 Total Cost
⚡ Buying Call Option: Buy 1 $50.00 Call at $10.00 Premium = $1,000.00 Total Cost
The total exercisable value of this option is $5,000.00 (right to buy 100 shares at $50.00). The cost to purchase the option ($1,000.00) is less upfront capital than the total exercisable value, the remaining $4,000.00 could be deposited and earn interest. This would be positively reflected in the value of the long call option as interest rates increase.
Practical Example: Negative Rho (Put Option)
⚡ XYZ has a current market price of $50.00
⚡ Shorting Stock Value: Sell 100 XYZ at $50.00 per Share = $5,000.00 Total Proceeds
⚡ Buying Put Option: Buy 1 $50.00 Put at $10.00 Premium = $1,000.00 Total Cost
The total exercisable value of this option is $5,000.00 (right to sell 100 shares at $50.00). The $5,000.00 from a short sale could be deposited and earn interest. This would be negatively reflected in the value of the long put option as interest rates increase.
Trading Implications
Interest rate risk has the greatest effect on longer-dated options (LEAPS). Under normal circumstances, interest rates move gradually, usually in 0.25 percentage-point steps when the Federal Reserve changes rates. Rho is generally less significant than other Greeks during stable interest rate environments but becomes more important in environments with significant interest rate changes.

What Your Greeks Should Look Like by DTE
Knowing what each greek means is step one. Step two is knowing what normal looks like at each stage of a trade. The table below follows a typical 0.30-delta short option, the kind you sell in a cash-secured put or covered call, from entry to expiration. I usually enter about 30 days out; the 45-day row is there because many sellers start earlier.
These are directional patterns, not fixed values. Actual numbers scale with the stock price and implied volatility. The pattern is what to memorize: vega risk early, gamma risk late, and the best balance of theta against gamma risk in between.
When to Roll: My 70 Delta Trigger
For a covered call I sold at 30 delta, my rule is mechanical. If the stock rallies and the call reaches 70 delta, I buy it back and sell a new call about 30 days out at about 30 delta, ideally for a net credit. At 70 delta, the call is meaningfully in the money and likely to finish there. We tested waiting until 80 or 90 delta, and 70 worked best, because at 70 you are still buying the call back at a price where you can go out and sell a new one that pays. It is not a panic button. It is a decision point: sell at 30, roll at 70. If you are happy to let the shares go, you can skip the roll and let them be called away.
Greek Targets by Strategy
Here is how the greeks translate into entry rules for the core income strategies I teach. I enter all four about 30 days out. Weeklies pay you sooner, but they pay less.
All four are positive theta and negative vega, which is the whole point: they get paid by the calendar and hurt by volatility spikes. Size them accordingly. On a condor I give the put side more room than the call side, because when the market falls, it tends to fall faster than it rises. And if the strikes those deltas give you leave only a narrow range around the stock price, I skip the trade.
How the Greeks Behave Around Earnings
Earnings are where traders who only know the definitions get hurt, because every greek temporarily changes character.
Pre-earnings premium is inflated implied volatility, not free theta. Option prices swell before a report because the market expects a big move. You can see how big: add up the prices of the at-the-money call and put (the straddle) in the first expiration after the report, divide by the stock price, and you get roughly the move the market is pricing in. That fat premium is payment for event risk. Time decay will not hand it to you early, no matter what the theta column says.
IV crush can beat your delta. The moment the report drops, implied volatility collapses. Say the options price in a 12% move and the stock moves only 4% your way. You were right on direction, and an at-the-money call bought before the report can still lose money, because the vega loss outweighs the delta gain. The Options Industry Council's vega primer explains how implied volatility drives this.
My rule: I do not sell options in front of earnings. A short option held through a report is a concentrated short-vega bet on a known event, and you do not know which way the stock will gap. Early on, we sold through earnings. Over time we found it was better to skip that month and wait, which also left more upside on the shares. So every week I check the earnings calendar for the stocks I trade before I sell anything. If you sell options for the steady theta income the rest of this page describes, sit out the report and sell after it.
Frequently Asked Questions About the Option Greeks
What are the option Greeks in simple terms?
They are five measurements of how an option's price reacts to different forces: Delta (stock price moves), Gamma (how fast Delta changes), Theta (time passing), Vega (volatility changes), and Rho (interest rates).
How many option Greeks are there?
There are five standard Greeks: Delta, Gamma, Theta, Vega and Rho. Vega is not actually a Greek letter, but it is treated as one. Professional desks also track second-order Greeks such as vanna, charm and vomma, but delta, gamma, theta and vega cover almost every decision a retail options trader makes.
Which Greek is most important for beginners?
Delta. It tells you both how much your option will move per $1 change in the stock and, roughly, the chance the option finishes in the money. A 0.30 delta call has about a 30% chance of being in the money at expiration. It is the Greek I use to pick every strike I sell.
Is Theta good or bad for me?
It depends which side of the trade you are on. Theta is the buyer's enemy because the option loses value every day, and the seller's friend because that daily decay becomes the seller's profit. That is why theta shows as negative on a long option and positive on a short one.
What is a good Delta for selling options?
Many income traders sell options around 0.20 to 0.30 delta, which implies roughly a 70% to 80% chance the option expires worthless and the seller keeps the full premium. Those odds are estimates, not guarantees, and a losing trade can cost much more than the premium a winning one collects. For covered calls I sell about 30 delta, a level we arrived at through backtesting. For puts, I usually sell around 25 delta.
Is Delta the probability of profit?
No. Delta approximates the probability that the option finishes in the money, not the probability of profit. A 0.30 delta call has roughly a 30% chance of finishing in the money, but the buyer only profits if the stock also clears the strike plus the premium paid, so the buyer's odds of profit are lower than 30%. For the seller, the premium works the other way, so the odds of at least some profit are a bit better than 100 minus delta.
What does Gamma mean in options?
Gamma measures how fast Delta changes when the stock moves $1. A 0.50 delta option with 0.05 gamma becomes a 0.55 delta option after a $1 rally.
Why is Gamma highest at the money?
Because that is where each $1 move has the biggest effect on the odds of finishing in or out of the money. Deep in- or out-of-the-money options barely change their behavior, so their Gamma approaches zero.
Is high Gamma risky?
For sellers, yes: high Gamma means the position's exposure can swing quickly, which is why short options get riskier near expiration when Gamma peaks. Buyers experience it as acceleration in their favor when the move goes their way.
What does Theta mean in options?
Theta is the amount of value an option loses each day from time passing alone. A theta of -0.05 means the option sheds about $5 per contract per day, all else equal. The buyer loses that $5 and the seller collects it.
Why does Theta accelerate near expiration?
Time value reflects the chance of a meaningful move before expiry. As days run out, that chance collapses faster and faster, so the final weeks see the steepest decay.
What does Vega mean in options?
Vega measures how much an option's price changes for each one-point move in implied volatility. A Vega of 0.10 means the option gains or loses about $10 per contract when IV rises or falls one point.
What is the theta to vega ratio?
Some option sellers divide theta by vega to compare how much daily decay a position earns for each point of implied volatility risk. Short-dated options have high theta and low vega, so the ratio rises as expiration approaches. The catch is gamma: the same short-dated options that score well on this ratio carry the most gamma risk, which is the trade-off the DTE table on this page shows.
Why does my option lose value after earnings even when I was right?
IV crush. Implied volatility inflates before the event and collapses after it, and Vega translates that collapse into a price drop that can overwhelm the directional gain. If the stock moves less than the market priced in, you can be right and still lose.
Which options have the most Vega exposure?
Longer-dated and at-the-money options. If you are buying time, you are also buying volatility exposure, so check where IV sits relative to its normal range before entering.
What should my delta be at 21 DTE?
There is no single right number. For a covered call I open around 0.30 delta about 30 days out (for puts, around 0.25). By 21 DTE, if the trade is working, delta has drifted lower and much of the easy decay is collected, so closing early is reasonable. On a covered call, if delta has climbed toward 0.70, that is my signal to roll out to a new 30-day, 30-delta call rather than hold and hope.
When should I roll a short option?
Roll when your rule says so, not when you panic. For covered calls I sold at 30 delta, my trigger is 70 delta: buy back the call and sell a new one about 30 days out at about 30 delta, ideally for a net credit. For short puts, rolling down and out can buy time if your thesis is still intact. Rolling buys time, not certainty, so if the thesis is broken, close the trade instead.
Which greeks matter most for covered calls?
Delta and theta. The delta of the call you sell sets how likely your shares are to be called away; I sell 30 delta and roll at 70 delta. Theta is the paycheck, since it is the reason the call you sold loses value as expiration approaches. Vega matters at entry because higher implied volatility means richer premiums, and gamma matters in the final two weeks when delta can swing quickly. Also check the earnings date before you sell: I do not sell covered calls in front of a report.
Can I download this options Greeks cheat sheet as a PDF?
Yes. The free 2-page PDF linked near the top of this page is a printable summary of the five Greeks, including the Greeks-by-DTE card. It is an instant download with no email required.
Keep Learning
📘 Options Break-Even Prices Explained
📘 Implied Volatility Explained
📘 Options Time Decay Explained
The Greeks finally click when you use them on real trades. That's how we teach them in the Options Trading in 21 Days course.
Stay Connected!
Join our mailing list to get notified of all new blog posts, and receive the latest news and updates from our team.
