
Vertical Spreads Explained: The Four Types and When I Use Each
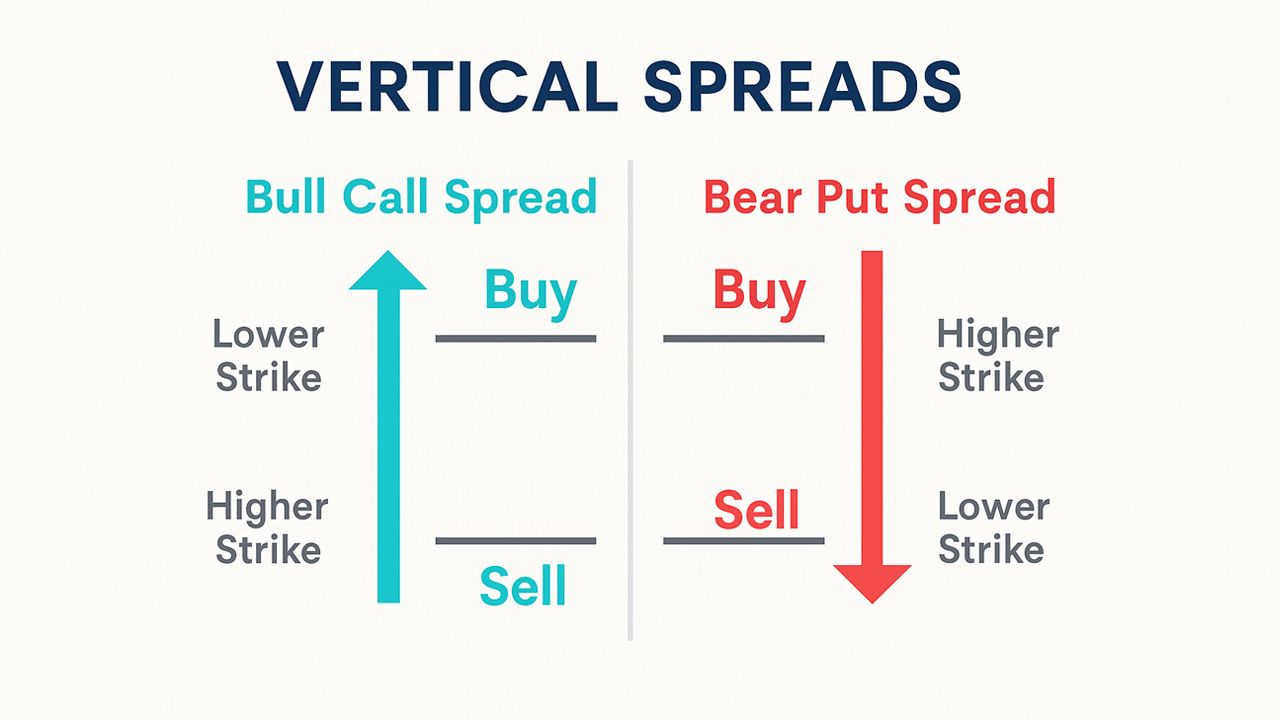
A vertical spread is an options trade that buys one option and sells another of the same type, on the same stock, with the same expiration, at a different strike price. The two legs together define your maximum profit and maximum loss before you enter, and they cost far less than a single option outright. There are four of them: two you pay to enter (debit spreads) and two that pay you (credit spreads), one bullish and one bearish of each.
I traded derivatives professionally for 22 years, and if I could only keep one structure from the whole options toolkit, it would be the vertical spread. Not because it is exciting. Because it is the trade that let me put positions on and then go hiking with my family without staring at a screen, knowing exactly what the worst case was. This article covers the four types with real numbers, why I moved from selling naked puts to selling put spreads, when a debit spread beats a plain call, and the mistakes I see new spread traders make every single time.
Key Takeaways
✅ A vertical spread buys and sells the same type of option (calls or puts) at different strikes, same expiration. Max profit and max loss are known before you click submit.
✅ Debit spreads (bull call, bear put) pay to enter and profit from a directional move. Credit spreads (bull put, bear call) collect premium and profit from time passing while the stock behaves.
✅ The width between strikes is your risk. Keep it $5 to $10 to start, and size it inside a 1 to 2% per-trade risk rule.
✅ Credit spreads free up capital: a broker holds the spread width, not 20% of the whole stock position, so you can diversify across more trades.
✅ When options are expensive (VIX above 20, definitely above 25), use spreads instead of single calls or puts. Simple spreads outperform complicated structures more often than not.
What Is a Vertical Spread?
"Vertical" just means the two options sit on top of each other on the options chain: same expiration column, different strike rows. You are long one strike and short another. The Options Industry Council lists them as the foundational two-leg strategies for exactly that reason.
Why bother with a second leg? Three reasons, and they are the same three every time:
⚡ It lowers the cost or the risk. The option you sell pays for part of the option you buy, or caps the loss on the option you sold.
⚡ It defines the outcome. You know the most you can make and the most you can lose the moment the trade fills. No guessing, no surprises.
⚡ It expresses a realistic view. Most stocks do not move 50% in a month. A spread pays you for a moderate move, which is the kind that actually happens.
The price you pay for those benefits is a cap. A spread will never hit the home run a single option can. I have made peace with that, because there is an old saying on trading floors that has held up for my entire career: you never go broke taking a profit.
The Four Vertical Spreads
Two variables give you four spreads: calls or puts, and whether you pay or collect. Here is each one with the setup, the math, and a worked example. Every "max profit" and "max loss" below is per contract, which is 100 shares.
1. Bull Call Spread (debit, bullish)
Buy a call at a lower strike, sell a call at a higher strike, same expiration. You pay a net debit and profit as the stock rises, with the gain capped at the short strike. Also called a long call spread or call debit spread.
📌 Buy the 135 call for $9.30. Sell the 150 call for $1.54. Net cost $7.76.
📌 Breakeven = 135 + 7.76 = $142.76. Max profit = (15 width minus 7.76) x 100 = $724. Max loss = $776.
Why not just buy the 135 call? Because then the stock has to climb to $144.30 before you make a dollar, and every day it does not, time decay is eating you. Selling the 150 call cut the cost by $154 and pulled the breakeven down. If you genuinely think the stock is going to $170, do not do this: buy the call and keep the upside. If you think it is going to $150, the spread is the better trade.
2. Bear Call Spread (credit, bearish or neutral)
Sell a call at a lower strike, buy a call at a higher strike. You collect a net credit and keep it if the stock stays below the short strike. Also called a short call spread or call credit spread.
📌 Sell the 142 call for $1.93. Buy the 145 call for $0.87. Net credit $1.06.
📌 Breakeven = 142 + 1.06 = $143.06. Max profit = $106. Max loss = (3 width minus 1.06) x 100 = $194.
This is the trade for "I do not think it gets above 142 in the next 30 days." You are not predicting a fall. You are predicting a ceiling, and getting paid for it.
3. Bear Put Spread (debit, bearish)
Buy a put at a higher strike, sell a put at a lower strike. You pay a net debit and profit as the stock falls, capped at the short strike. Also called a long put spread or put debit spread.
📌 Buy the 800 put for $44.88. Sell the 750 put for $22.63. Net debit $22.25.
📌 Breakeven = 800 minus 22.25 = $777.75. Max profit = (50 width minus 22.25) x 100 = $2,775. Max loss = $2,225.
Same logic as the bull call spread, pointed down. If you think a stock is going to fall 10 or 15%, this pays you for that move at roughly half the cost of the put alone.
4. Bull Put Spread (credit, bullish or neutral)
Sell a put at a higher strike, buy a put at a lower strike. You collect a net credit and keep it if the stock stays above the short strike. Also called a short put spread or put credit spread. This is the one I trade most, and the next section is about why.
📌 Sell the 145 put for $6.60. Buy the 135 put for $3.07. Net credit $3.53.
📌 Breakeven = 145 minus 3.53 = $141.47. Max profit = $353. Max loss = (10 width minus 3.53) x 100 = $647.
Why I Moved From Selling Puts to Selling Put Spreads
Selling puts works. I still do it on the right stocks. But when you sell a naked put, two things eventually become limiting factors: capital and risk. Here is the example I use with every student.
A stock is trading at $57. You sell ten of the $50 puts for $1.00 and bring in $1,000. Your broker knows that if you are assigned, you will need $50,000 to buy the shares, so it segregates a chunk of your account against that possibility. Every firm is different, but call it 20%, which is $20,000 of a $100,000 account that you now cannot use for anything else. And if bad news hits and the stock falls to $30, you are still buying at $50. On ten contracts that is a $20,000 loss.
Now the same trade as a spread. You sell the $50 puts for $1.00 and buy the $45 puts for $0.25. You bring in $750 instead of $1,000. In exchange:
✅ Your max loss is the width minus the credit: $5.00 minus $0.75, or $4.25 per share, $4,250 on ten contracts. The stock can go to zero and that number does not change.
✅ Your broker only holds the $5,000 spread width, not $20,000. The other $15,000 is free to put into spreads on other stocks, which is how you diversify an income portfolio.
✅ You can go to work, go golfing, go on vacation. There is nothing to manage in a panic because the worst case is already on the ticket.
You gave up $250 of premium for control of the trade. Over 22 years I never once regretted that exchange, and I regretted the times I skipped it. Selling a $55 put on a $60 stock feels safe right up until the company pre-announces, loses a major customer, and opens at $30. The hedge is what separates income trading from speculation dressed up as income. The single-leg version and its risks are in Is Selling Put Options Safe?
How I Build a Credit Spread, Step by Step
1️⃣ Pick a stock you are at least neutral on. Ideally slightly bullish for a put spread, and ideally a stable, conservative name, not the biotech with a trial readout next month. Big premium on a risky stock is not a gift; it is compensation for a risk you may not have noticed.
2️⃣ Sell the short strike where you are confident the stock stays. For puts I go a little more conservative than my covered-call rule: a 25 to 30 delta, because downside implied volatility is always a bit richer, so you get paid more for a bigger buffer. Delta is the market telling you the probability: a 30-delta put has roughly a 70% chance of expiring worthless.
3️⃣ Buy the long strike where your personal max loss lives. Five points below, ten at most to start. Some people cannot stomach more than a $2,500 loss and buy the hedge $2.50 away. That is fine; the tighter hedge costs more premium, and that is the trade-off you are choosing.
4️⃣ Go about 30 days out. Long enough for time decay to work, short enough that if it goes wrong you can reset next month.
5️⃣ Check the width against your account. A $5 spread on ten contracts is $5,000 of risk. In a $25,000 account that is 20% on one trade, which violates the 1 to 2% rule by a mile. Trade one contract, or a narrower spread, or move on.
6️⃣ Preview the order and read it back to yourself. Most platforms show max loss on the confirmation screen. If you expected $500 and it says $5,000, you grabbed the wrong leg or forgot the hedge. I did this for a living and still read every order aloud twice before sending.
The same steps run in reverse for a bear call spread. The iron condor, which is simply a put spread and a call spread on the same stock at the same time, is covered in Weekly Iron Condors for Income.
When Should You Use a Debit Spread Instead of a Single Call or Put?
Being right on direction is not enough with a single option. You could buy a call, watch the stock go up, and still lose because it did not go up enough to cover what you paid for time and volatility. A debit spread fixes the pricing problem, not the direction problem.
Say a stock is at $52 and the $52.50 call costs $5.00 because implied volatility is high. The stock has to reach $57.50 before you make a dollar. Sell the $60 call against it for $2.00 and the trade now costs $3.00, your breakeven drops to $55.50, and you have sold some of that expensive volatility back to the market. You gave up everything above $60. If you did not think it was going above $60 anyway, you gave up nothing.
My mental filter is short:
📌 Use the spread when options are expensive (VIX above 20, definitely above 25), when you expect a moderate move of 10 to 15% rather than a blowout, or when you want a higher probability of a profit and are willing to cap it.
📌 Use the single option when you expect a strong, fast move with a real catalyst, when volatility is unusually cheap relative to its own history, or when you simply want full upside and know you are paying for it.
For the debit side, buy near the money, around a 50 to 55 delta, and sell the strike where you think the move ends. Give the spread enough width to matter: if you paid $5.00 for the long leg, a strike five points away leaves you nothing. Time frame follows the thesis. An earnings catalyst 28 days out wants a 45 to 60 day option, not a one-year LEAP. A six-month story wants nine months of runway. The Greeks cheat sheet is where the delta numbers come from if you want to go deeper.
Managing the Trade After It Is On
For a credit spread there are three scenarios and only one of them needs you.
✅ Stock stays above the short strike. Do nothing. Let it decay and keep the premium. This is the outcome you are trading for every single time.
⚠️ Stock drifts toward the short strike. Monitor it and decide: hold and accept a small loss if it finishes between the strikes, or roll the spread down and out to buy time. With a naked put you have to make this call constantly. With a spread you make it rarely, because the hedge is already on.
❌ Stock breaks below both strikes. You already know the number. Close early and take the loss, or let it expire at max loss. Either way it is the loss you signed up for, not a surprise.
For a debit spread, decide the exit before you enter. If you own the 60/70 call spread and the stock is at $73, are you closing for most of the gain or holding to expiration for the last few cents? Write it down. No plan for the exit is the mistake that turns winners into scratches.
The Mistakes I See Most
❌ Strikes too far apart. Buying a $3.00 call and selling one 30 points away for $0.20 is not a spread, it is a call with a rounding error. The short leg has to actually cheapen the trade.
❌ Using a spread to justify an overpriced option. When a stock is all over the news and volatility is extreme, even the spread version is expensive. Sometimes the answer is to sit out.
❌ Oversizing because the risk is "defined." A capped loss of 10% of your account is still a 10% loss. Define the risk, then size it at 1 to 2%.
❌ Getting clever too early. Once spreads feel comfortable, people jump to butterflies, straddles, risk reversals, one-by-twos. I will be straight with you after 22 years: simple spreads usually perform better than the complicated ones, because with the complicated ones you have to be dead on, and markets rarely do exactly what you expect.
Your First Spread
Do it in a paper account. Pick a familiar, boring stock or an index ETF like SPY. Go out 30 days. Sell a put about 25 to 30 delta below the price, buy the put $5 below that (or $2.50 if you want to be extra conservative), one contract. Before you send it, say out loud what your max profit and max loss are. Then watch it for 30 days. The goal is not to make money. It is to understand the structure so well that when you do it with real money, nothing about it feels new.
Vertical spreads are where options stop being lottery tickets and start being a repeatable process: defined risk, realistic targets, and premium collected on the probability that the market itself hands you. Learn them properly and most of what comes after is a variation on the same two legs.
Frequently Asked Questions About Vertical Spreads
What is a vertical spread in options?
A two-leg trade that buys one option and sells another of the same type and expiration at a different strike. The combination defines your maximum profit and loss up front and costs less than a single option. Debit spreads pay to enter and profit from direction; credit spreads collect premium and profit from time passing.
What are the four types of vertical spreads?
Bull call spread and bear put spread (debit spreads you pay for), and bull put spread and bear call spread (credit spreads that pay you). Bull spreads profit when the stock rises or holds; bear spreads when it falls or holds.
How wide should a vertical spread be?
Start at $5 to $10 between strikes, and narrower if your account is small. The width minus the credit is your maximum loss on a credit spread, so pick a width that keeps a full loss inside 1 to 2% of your account. On a debit spread the width has to be wide enough that the trade can still pay after what you spent on the long leg.
Are vertical spreads good for beginners?
Yes, once you understand single calls and puts. Defined risk on both sides makes spreads one of the safest ways to trade a view, they need less capital than naked puts, and they need far less babysitting. They are the structure I recommend for most people, most of the time.
Every spread, built and managed step by step, is inside the Options Trading in 21 Days course.
Keep Learning
📘 The Complete Beginner Guide to the Put Credit Spread
📘 Weekly Iron Condors for Income: A Practical Guide for Traders
📘 Options Trading for Beginners in 2026: A Complete Guide
Defined risk is not a limitation. It is the whole point. Learn to trade that way inside the Options Trading in 21 Days course.
Stay Connected!
Join our mailing list to get notified of all new blog posts, and receive the latest news and updates from our team.
